DSCR Loan Illinois: Rental Property Financing That Qualifies on Cash Flow
Qualify on the property’s rental income — not your tax returns. No W-2s, no minimum credit score or DSCR, close in an LLC.
- Qualify on Rental Income
- No Tax Returns or W-2s
- No Minimum Credit Score or DSCR
- Up to 85% LTV
AAPL Member · Direct Lender Since 2016 · NMLS #1979189
Written and reviewed by Kyle Farmer, Lead Account Executive, Tidal Loans
This page was written and reviewed by Kyle Farmer, who works on dscr and rental loans at Tidal Loans daily. Terms are checked against our current underwriting guidelines; last reviewed October 2026.
Illinois is one of the strongest cash-flow rental states in the Midwest, anchored by Chicago’s two- to four-flat stock and supported by steady demand in the collar counties and downstate. A DSCR loan in Illinois lets you put those rents to work, qualifying on the property’s rental income instead of your personal income — no tax returns, no W-2s, no debt-to-income ceiling. If the rent covers the mortgage, you have a path to funding. Tidal Loans has financed Illinois investors as a direct lender since 2016, and our DSCR program is built to help you scale a buy-and-hold portfolio.
We finance single-family and 2–4 unit rentals, multifamily and mixed-use, Airbnb and VRBO vacation homes, and properties across the state. Many investors search for a “rental property loan in Illinois,” and that’s exactly what this is — a long-term rental property loan carried by the property’s cash flow. For how the product works nationally, see our DSCR loan program.
What Is a DSCR Loan?
A DSCR loan is a mortgage for investment property approved on the property’s rental income instead of your personal income. No tax returns, no W-2s, no debt-to-income ceiling. We have no minimum credit score and no minimum DSCR — we fund below 1.0 and below 0.75, with terms adjusting to the ratio.
DSCR stands for Debt Service Coverage Ratio — the metric that compares a rental property’s income to its debt payments. A DSCR loan is a non-QM (non-qualified mortgage) product that qualifies borrowers on property cash flow rather than personal income or tax returns. Instead of looking at your personal debt-to-income ratio the way a bank would, we look at whether the property’s rent can cover its mortgage, taxes, and insurance. That makes DSCR loans in Illinois ideal for self-employed investors, LLCs, and anyone scaling a rental portfolio past conventional limits.
How Do You Calculate DSCR?
Divide the property’s net operating income by its total annual debt service. A 1.0 ratio means the rent exactly covers the payment. We have no minimum, so a ratio below 1.0 is not a decline — it means lower leverage, a higher rate, or more reserves.
The formula is straightforward:
DSCR = Net Operating Income (NOI) ÷ Total Debt Service
NOI is the rental income after operating expenses — for 1–4 unit rentals you can use the gross rent, and for short-term rentals we can use projected income based on market rates. Total Debt Service is the annual mortgage payment including principal, interest, taxes, and insurance. A DSCR of 1.25 means the property earns 25% more than its debt payment — a healthy cushion. Most lenders set a 1.20–1.25 minimum, but we take a more flexible approach with no strict minimum, funding ratios as low as 0.75 (and below) by adjusting the loan-to-value and rate. Our DSCR calculator runs your specific numbers in seconds.
DSCR Loan Illinois Requirements
Because the property carries the loan, qualifications focus on the asset rather than your paystubs:
- Credit: credit-flexible — we work with a wide range of credit profiles, with better terms at higher scores.
- No minimum DSCR — we fund below 1.0 and below 0.75; higher ratios earn better terms, and lower ratios are funded with adjusted LTV and pricing.
- Rent-ready property — it should be in habitable, rentable condition. An active lease at closing is a plus but not required.
- Down payment — up to 85% LTV on purchases (as little as 15% down), or 20%+ equity on a refinance.
- Investment use only — non-owner-occupied: purchase, refinance, or cash-out.
We fund the full range of Illinois investment property — single-family, 2–4 unit, multifamily and mixed-use, and commercial — and you can close in an LLC so the loan stays off your personal credit report.
DSCR Loans Across Illinois’ Major Markets
We make DSCR loans across Illinois, and Chicago drives most of our volume. The city’s older single-family homes and two- to four-flats are built for flips and BRRRR, and they rent reliably once stabilized. The collar-county suburbs move at higher prices with faster turnover. Downstate markets offer the strongest cash flow per dollar invested.
Chicago
Chicago is our busiest Illinois market by a wide margin. Its two- to four-flats and older single-family stock give investors both scale and rent reliability. Our DSCR lenders in Chicago qualify your loan on the property’s rent, so you can keep buying past the point a conventional lender would stop counting.
The Collar Counties
Naperville, Aurora, Joliet and Schaumburg bring higher values and steady suburban rental demand. Our DSCR lenders in the Chicago suburbs finance single-family and small multifamily rentals for investors building long-term cash flow outside the city.
Rockford, Springfield, Peoria & Champaign
Downstate Illinois is where the cash-flow math works most easily: low entry prices against solid rents. We fund DSCR rentals across Rockford, Springfield, Peoria, Champaign and the surrounding areas.
Beyond these, we finance DSCR rentals in Evanston, Oak Park, Cicero, Bloomington and across the state.
Benefits of a DSCR Loan in Illinois
DSCR loans give Illinois investors advantages conventional financing can’t match, because approval rests on the property’s income rather than your personal debt-to-income ratio. Key features include:
- Approval on property cash flow — no personal income verification, tax returns, or pay stubs.
- No seasoning on cash-out refinances — renovate, raise the rent and value, and refinance shortly after with no waiting period, ideal for a strong BRRRR market.
- Low down payment — as little as 15% down (up to 85% LTV).
- Interest-only options — up to 10 years interest-only, then amortize at the same fixed rate with no ARM resets.
- No minimum DSCR — we fund below 1.0 and below 0.75, with terms adjusted to the ratio.
- Short-term rental income counted — we use Airbnb/VRBO market rates for qualification, valuable in vacation and event markets.
- Close in an LLC — keep the loan off your personal credit and protect your borrowing capacity.
- Flexible on the edges — foreign nationals, non-warrantable condos, vacant rent-ready properties, and first-time investors all welcome.
Instead of proving personal income or capping your growth at your salary, you leverage each property’s cash flow.
Airbnb & Short-Term Rental Financing in Illinois
Illinois short-term rental demand is concentrated in Chicago, where business travel, conventions and year-round events fill nightly rentals, and in lake and river getaway markets like Galena and the Lake Michigan shoreline. Traditional lenders often hesitate to count Airbnb income, but our DSCR program is built for it. When you’re buying a short-term rental, we consider the projected short-term income using market rates rather than a long-term lease figure, so the higher earning potential helps you qualify. The full program lives on our Illinois Airbnb financing page.
Tidal Loans — Illinois’ Trusted Private DSCR Lender
Tidal Loans is a direct private lender, built and backed by real estate investors. Since 2016 we’ve helped Illinois investors finance rentals across the state, underwriting the property’s cash flow rather than your personal income and moving quickly with in-house decisions. Many of our Illinois investors run the BRRRR strategy — buy, rehab, rent, refinance, repeat — and Chicago’s two- to four-flat stock is ideal for it. They acquire and renovate with our hard money loans in Illinois, place a tenant, then refinance into a long-term DSCR loan that pays off the short-term debt and pulls their capital back out through a cash-out refinance with no seasoning required. For larger deals, our multifamily lending program covers apartment and mixed-use properties.
A Recent Illinois DSCR Cash-Out We Funded
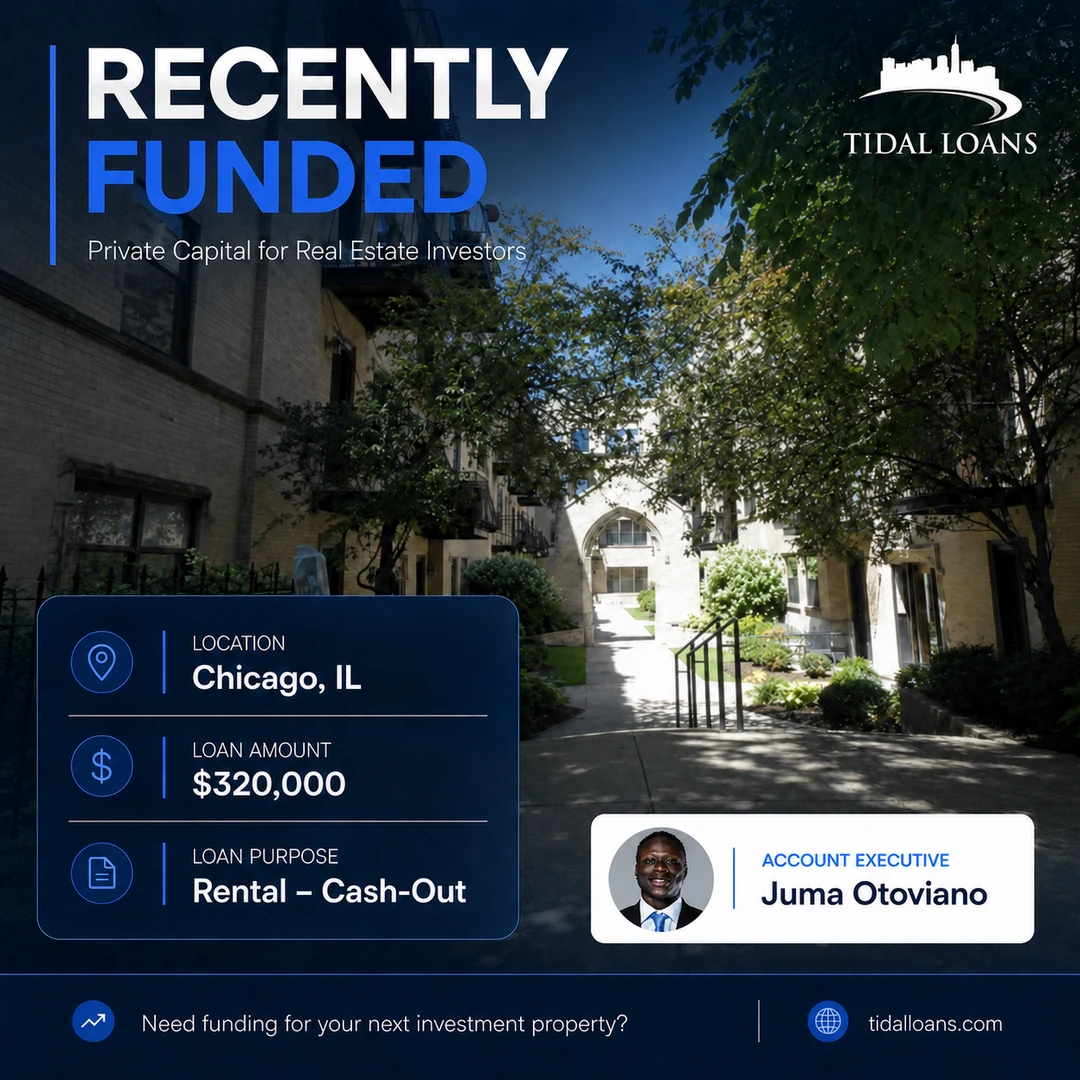
$320,000 Rental Cash-Out Refinance in Chicago, IL: Equity Redeployed Into a Commercial Purchase
Tidal Loans funded a $320,000 cash-out refinance at 80% loan-to-value on a Chicago rental property. The investor used the released equity to acquire a commercial property, moving capital out of a stabilised rental and into the next acquisition without having to sell the original asset.
Account Executive: Juma Otoviano
Pulling equity out of a performing rental is often cheaper than selling it, because a sale ends the rental income, triggers transaction costs and starts a tax clock. A cash-out refinance keeps the asset and its cash flow in place while freeing the capital for the next purchase.
Want it run by an actual underwriter before you commit?
Frequently Asked Questions
Yes — we lend statewide and are active across the Chicago metro, the collar counties and downstate markets like Rockford, Springfield, Peoria and Champaign. We qualify every loan on the property’s rental income. Chicago’s two- to four-flats in particular make it one of the strongest BRRRR markets in the Midwest.
Essentially, yes. A DSCR loan is a type of rental property loan that qualifies on the property’s cash flow — the rent versus the mortgage payment — instead of your personal income. So whether you’re searching for a “DSCR loan” or a “rental loan” in Illinois, our program is the same product: long-term financing for buy-and-hold investors with no tax returns or W-2s required.
Yes. We specialize in Airbnb DSCR loans and use projected short-term rental income to qualify your loan rather than limiting you to a long-term lease rate. Whether it’s a Chicago city rental serving business and convention travel or a getaway property in Galena, we evaluate short-term income using market data.
Most purchases go up to 85% LTV (as little as 15% down; typical deals 20–25% down), or 20% equity on a refinance. A stronger DSCR and higher credit score can improve your terms. You won’t need tax returns, pay stubs, or employment history — just a rent-ready property and solid rental cash flow. We evaluate lower-ratio and lower-credit deals case by case and can often still structure a workable loan.
A hard money loan is short-term financing for buying and renovating a property, while a DSCR loan is long-term financing that qualifies on the stabilized property’s rental income. Many Illinois investors use both in sequence: hard money to acquire and rehab, then a DSCR loan to refinance into a permanent hold. If your property is already rented and stabilized, you’d go straight to a DSCR loan.
Ready to fund your Illinois deal?
Get a fast quote from a direct lender — or call and walk it through with us.