Airbnb & Short-Term Rental Loans in Indiana
Finance your Airbnb or VRBO the way it actually earns — qualified on the property’s short-term rental income, not your W-2.
- Qualify on STR Income
- No Tax Returns
- Up to 75% LTV
- 30-Year Fixed Available
AAPL Member · Direct Lender Since 2016 · NMLS #1979189
Written and reviewed by Cameron Montgomery, Account Executive, Tidal Loans
This page was written and reviewed by Cameron Montgomery, who works on airbnb loans at Tidal Loans daily. Terms are checked against our current underwriting guidelines; last reviewed October 2026.
Indiana has solid short-term rental markets — Indianapolis generates major event demand around the Indy 500, conventions, and sports, Brown County and Nashville are a popular cabin and fall-foliage getaway, and the Lake Michigan shoreline draws summer visitors. But financing a vacation rental trips up most investors, because the property usually has no long-term lease and conventional lenders don’t know how to underwrite nightly income. Airbnb loans in Indiana from Tidal Loans solve that — we qualify your loan on the property’s projected short-term rental income, not your personal income. We’ve financed Indiana short-term rental investors as a direct lender since 2016.
How Do You Finance an Airbnb in Indiana?
With a DSCR loan qualified on the property’s rental income rather than your tax returns. We can use projected short-term rental income, so the property does not need a long-term lease in place. Short-term rental financing goes up to 75% LTV, and you can close in an LLC.
An Airbnb loan is a DSCR loan built for short-term rentals. DSCR stands for Debt Service Coverage Ratio — we compare the property’s income to its debt payments, and if the income covers the mortgage, the deal qualifies. The difference with a short-term rental is the income side: instead of a long-term lease, we use the property’s projected short-term rental income, drawn from market data sources like AirDNA, to calculate the ratio. That means the higher nightly and seasonal rates a strong Indianapolis event rental or Brown County cabin commands actually help you qualify, rather than being ignored the way a bank would.
Because it’s underwritten on the property, there’s no personal income verification — no tax returns, no W-2s, no debt-to-income ceiling. You can close in an LLC and get long-term financing on a short-term rental: 30-year fixed terms, with interest-only options available. Run your numbers with our DSCR calculator, and see the full program on our Airbnb loan hub.
Indiana Short-Term Rental Markets
We finance short-term rentals across Indiana. Indianapolis draws event demand around the Indy 500, conventions and major sporting events. Brown County and Nashville, Indiana form a top Midwest cabin market. The Lake Michigan shoreline around Michigan City brings summer visitors, and Bloomington adds university demand. Indiana protects STRs at the state level, but cities can still require registration.
We finance short-term rentals across the state’s STR markets. Indianapolis generates strong event-driven demand around the Indy 500, conventions, and major sporting events, on top of steady year-round travel. Brown County and Nashville, Indiana are one of the most popular cabin and fall-foliage getaway markets in the Midwest. The Lake Michigan shoreline around Michigan City draws summer beach visitors, and Bloomington adds university and event demand. We finance vacation rentals across all of these markets and throughout Indiana.
A note on local rules: Indiana has state-level protections for short-term rentals, but individual cities can still impose registration or permitting requirements, so the rules vary by market. Part of our underwriting is confirming your property can legally operate as a short-term rental, so we’ll review the local rules and any required permit before funding.
What Are the Terms on an Indiana Airbnb Loan?
Up to 75% LTV on a short-term rental purchase, investment property only, with loan amounts from $75,000 to $5,000,000. Thirty-year amortisation and interest-only options are available. No minimum credit score and no minimum DSCR — a weaker ratio means lower leverage, not a decline.
Loan Details
Recovering Your Capital: the BRRRR Path
A zero-down Airbnb purchase isn’t realistic. We lend up to 75% LTV, so you bring a down payment. You can recover that cash with BRRRR. Buy and renovate with an Indiana hard money loan, then refinance the stabilized short-term rental into a DSCR loan with a cash-out refinance. That pulls your capital back out for the next property.
A pure zero-down Airbnb purchase isn’t typically realistic, since we lend Up to 75% LTV on a purchase and you’ll bring a down payment. But you can recoup that cash through the BRRRR strategy. If you buy and renovate a property with an Indiana hard money loan, then refinance the stabilized short-term rental into a DSCR loan with a cash-out refinance, you can pull your original capital back out and redeploy it into the next Indiana vacation rental. For straightforward long-term holds, our rental property loan program covers the buy-and-hold side.
A Recent Indiana Airbnb Loan We Funded
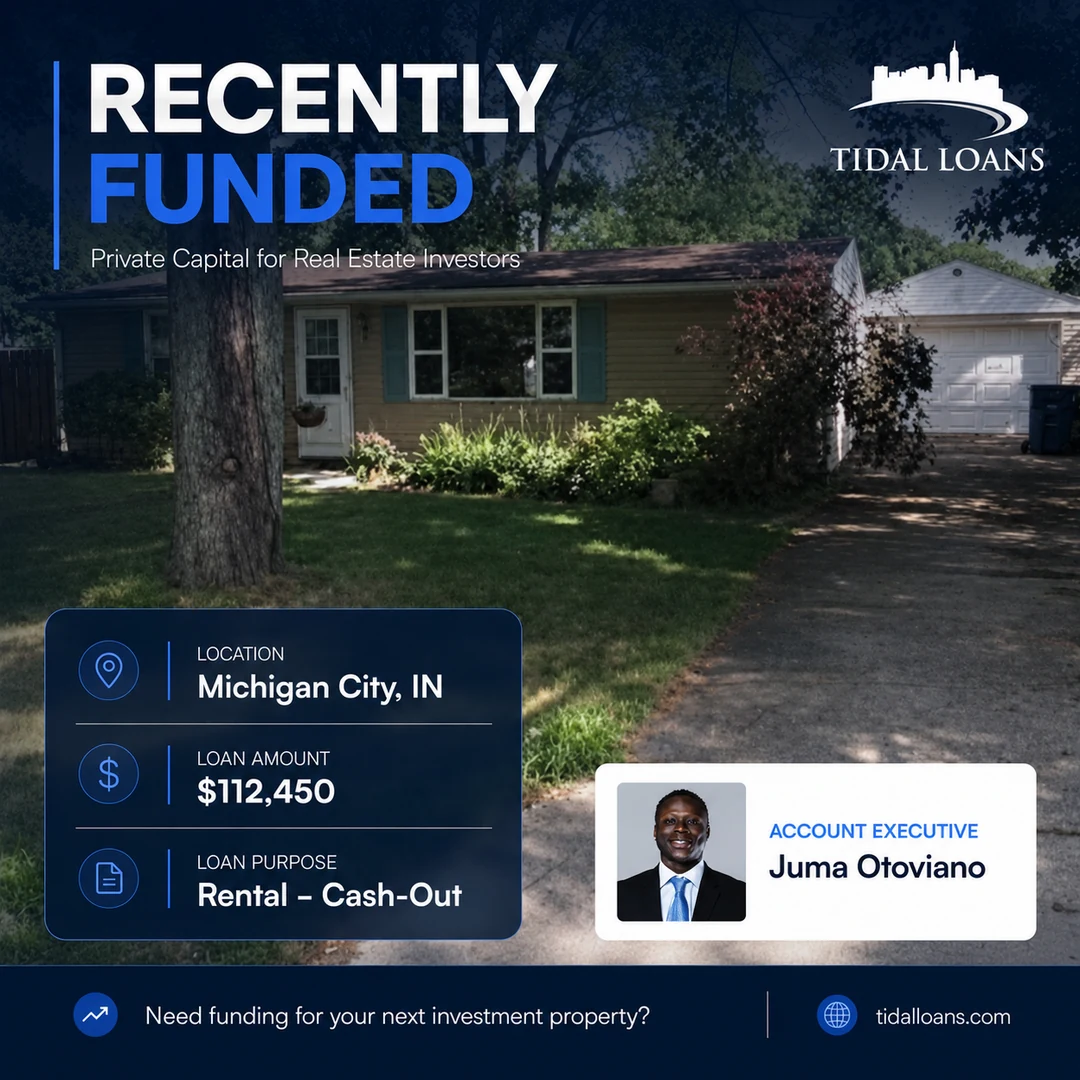
$112,450 Airbnb Cash-Out Refinance in Michigan City, IN: Equity Released After Eight Months
Tidal Loans funded a $112,450 cash-out refinance on a short-term rental in Michigan City, Indiana, after only eight months of ownership. We financed 75% of the property's value, letting the investor pull equity out of the Airbnb without selling it or waiting through a longer seasoning period.
Account Executive: Juma Otoviano
Michigan City sits on the southern shore of Lake Michigan, where short-term rental demand is driven by tourism and seasonal travel rather than the year-round patterns of an urban rental market. Washington Park Beach, Indiana Dunes National Park and South Shore Line rail access into Chicago all feed that visitor base.
Want it run by an actual underwriter before you commit?
Frequently Asked Questions
We use projected short-term rental income from market data sources like AirDNA, which estimates daily booking rates and occupancy for the property’s specific Indiana market. That projected income goes into the DSCR calculation against your proposed mortgage payment, giving you credit for the higher event-season and nightly rates a strong Indianapolis or Brown County rental earns, instead of capping you at a long-term lease figure.
Yes. Indiana has state-level protections for short-term rentals, but cities can still set their own registration or permitting rules, so it varies by market. Part of our underwriting is confirming your property can legally operate as an Airbnb, and we’ll ask for any required permit. We also recommend knowing the property’s fallback long-term rent, so the deal still works if local rules change.
Short-term rental loans are credit-flexible but typically expect a stronger profile than a standard long-term DSCR loan, given the income variability. A higher score improves your rate and terms. Because the property’s projected income carries most of the underwriting, your credit matters less than it would at a bank, but it still factors into your pricing and leverage.
Usually not. SBA and conventional business loans are built for owner-operated businesses, not investment property, and tend to be slow and restrictive. A DSCR-based Airbnb loan is purpose-built for investors — faster, underwritten on the property’s income, and closed in your business entity. For an investment short-term rental, it’s almost always the better fit.
We lend statewide, with especially strong activity in Indianapolis, Brown County and Nashville, the Lake Michigan shoreline, and Bloomington. Brown County in particular is one of the most popular getaway markets in the Midwest, while Indianapolis offers strong event-driven demand. Each market has its own demand patterns and local rules, and we structure the loan around the property’s projected income and confirm it can operate legally as a short-term rental.
Ready to fund your Indiana deal?
Get a fast quote from a direct lender — or call and walk it through with us.